Last updated November 18, 2026
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Construction Emergency Preparedness Guide for Doral Homes
After Hurricane Irma, the average Doral homeowner waited 47 days for a licensed contractor to perform emergency repairs. Not because contractors were unavailable. Because homeowners couldn’t produce the documentation their insurance adjuster required to authorize the work. That gap between damage and documentation is where most Doral recovery stories go wrong, and it’s entirely preventable. This guide covers the pre-event photo package insurers actually want, what HO-3 policies count as emergency mitigation, the four signs a flooded slab-on-grade home may have shifted, and the contract language that keeps a post-storm repair from becoming a second disaster.
Quick Answer
Construction emergency preparedness in Doral means assembling three things before a storm: a cloud-stored documentation package that establishes pre-loss condition, a written contact list of licensed contractors and your insurer’s claim line, and a pre-agreed emergency scope of work with a capped hourly rate. Homes that have these in place recover in weeks; homes that don’t spend those weeks arguing with adjusters and chasing unlicensed storm chasers.
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
Table of Contents
- The Pre-Event Documentation Package
- Emergency Tarping and Board-Up: What HO-3 Actually Covers
- The 60-Second DBPR License Check
- Structural Safety After Flooding: Four Signs to Watch
- FEMA Individual Assistance: What It Covers and What It Doesn’t
- Emergency Contractor Agreements: The Terms That Protect You
- Common Mistakes to Avoid
- When to Call a Professional
The Pre-Event Documentation Package
Your insurance adjuster’s job is to establish pre-loss condition before authorizing a payout. If you can’t prove what your roof looked like before the storm, your claim starts behind. Doral sits in a high-wind zone where shingle loss and soffit damage are routine after a tropical system, so the photo package matters more here than in most of Florida.
Shoot these angles, and shoot them in daylight with your phone’s location tagging on:
- Roof: Each slope from ground level at an angle, plus close-ups of ridge caps, flashing around vents and chimneys, and the drip edge where shingles meet the fascia.
- Windows and doors: Inside and outside of every opening, with a close-up of the manufacturer label. If you have Therma-Tru or ViewLux units, photograph the brand plate on the frame. Adjusters match specs to model numbers.
- Exterior walls: Straight-on and oblique shots of each elevation showing the weep screed, stucco finish, and any existing hairline cracking. Date-stamped photos of hairline cracks before a storm protect you from being blamed for post-storm movement.
- Fencing: Full-run photos of your fence line. Post-Irma, fence claims in Doral were routinely denied for lack of proof that panels existed before the wind. If your fence is Barrette or Master Halco, photograph the post caps and rail brackets that identify the system.
- Interior: Every room, wide shots plus close-ups of ceilings and under-sink cabinets. Water intrusion evidence disappears fast.
Store everything in cloud storage with a dated folder structure, not on a local drive that floods with the house. Email the package to yourself and your insurer once a year. The customers who recover fastest from a Doral storm are the ones whose adjuster opens a folder, not a negotiation.
Emergency Tarping and Board-Up: What HO-3 Actually Covers
A standard HO-3 policy treats emergency mitigation as a covered loss up to policy limits, but only for work that prevents further damage. Tarping a breached roof and boarding broken windows qualifies. Replacing the roof does not. That distinction decides whether your $4,000 tarp job is reimbursed or denied.
In our experience, emergency tarping and board-up on a Doral single-family home runs $2,500 to $5,000 depending on roof pitch, square footage, and how many openings need covering. Get it in writing before anyone climbs a ladder:
- Ask for a written scope listing square feet of tarp, number of openings boarded, and the material spec.
- Confirm the company’s license in the DBPR database before the truck unloads.
- Photograph the damage before mitigation, then photograph the finished tarp or board-up. Your insurer needs both.
- Get a receipt showing labor and materials separately. Adjusters reimburse materials at cost plus a markup, not at the flat “emergency rate” a storm chaser may quote.
Clause 1 of the Haven Standard exists because of exactly this: the price goes in writing before the work starts, even in an emergency. No verbal “we’ll settle up after the insurance check.” That sentence is how post-disaster disputes begin.
The 60-Second DBPR License Check
Florida’s Department of Business and Professional Regulation keeps a free public database at myfloridalicense.com. Look up any contractor before allowing them on your roof. The check takes under a minute and it filters out the unlicensed crews that flood Doral after every named storm.
- Open the DBPR license search.
- Enter the company name or the license number from the truck.
- Confirm the license type matches the work: a roofing contractor license for roofing, a general contractor for structural repair.
- Check the status is “Current, Active” and the expiration date hasn’t lapsed.
- Look at the complaint history. You’re reading for pattern, not perfection.
Unlicensed storm chasers count on you not doing this. They knock while the power is still out, quote a flat cash price, take a deposit, and are in another county before your adjuster sees the work. In a Doral recovery, unlicensed repairs also void future insurance claims on the same area. Florida statute is clear: work performed without a license can be ruled non-covered even when the damage itself was covered.
Our own crews are background-checked and uniformed, and we’ll show the license on the page before we ever knock. Ask the same of anyone else.
Structural Safety After Flooding: Four Signs to Watch
A slab-on-grade home that took floodwater or storm surge can shift on its foundation without dramatic collapse. The warning signs are quiet. Before re-entry after flooding, look for these four:
- Door gaps: A door that suddenly swings open or won’t latch because the frame has moved. Check the gap at the top of each door against the jamb.
- Diagonal cracking: Stair-step cracks running along block joints, or diagonal cracks at the corners of window and door openings. Hairline vertical cracks are normal; diagonal cracks that trace block courses are not.
- Sticking windows: Windows that operated fine before the flood and now bind in the frame. That’s a frame dimension change, not a lubricant problem.
- Visible grade separation: A gap between the slab edge and the surrounding soil, or soil that has dropped away from the foundation line by more than an inch.
If you see more than one of these, get a licensed structural engineer before you re-enter and especially before you call a contractor to start repair. A contractor who quotes you a rebuild without checking the foundation is quoting the wrong job. This is the step where Doral homeowners most often skip ahead, and it’s the one that decides whether the repair holds.
Our technicians have up to 19 years of experience reading these signs on South Florida slabs, and we’ll tell you when the answer is “call an engineer first.” That’s not a lost sale. It’s the right call.
FEMA Individual Assistance: What It Covers and What It Doesn’t
FEMA Individual Assistance is available when the President issues a major disaster declaration covering Miami-Dade County, which happened after Irma. The application window typically opens with the declaration and runs 60 days, though FEMA can extend it. Register at disasterassistance.gov or by phone; you’ll need your Social Security number, insurance information, damage photos, and proof of occupancy.
What FEMA does cover for construction:
- Minimal home repairs to make the residence safe, sanitary, and functional, at a capped amount set per disaster.
- Temporary housing assistance while your home is uninhabitable.
- Replacement of essential household items, at limited amounts.
What FEMA does not cover:
- Full reconstruction or bringing a home up to current code.
- Repairs already covered by your HO-3 policy, which is why you file with insurance first.
- Cosmetic repairs or upgrades.
FEMA is a bridge, not a rebuild. The gap between the FEMA cap and a full repair on a Doral home is real, and it’s the reason the documentation package and insurance claim come first. FEMA’s awards are reduced by any insurance settlement on the same damage.
Emergency Contractor Agreements: The Terms That Protect You
Verbal agreements made in the chaos after a storm are the single largest source of post-disaster contractor disputes in South Florida. When you’re signing an emergency repair contract, the language matters more than the price. Insist on these terms:
- Written scope before work begins: Square footage, materials by brand and spec, number of openings, removal and disposal included or not. “Emergency repair” is not a scope.
- Hourly rate cap: If the contract is time-and-materials, a hard ceiling on the hourly rate, written in. Billed hours can vary; the rate cannot.
- Change order discipline: No additional work until a written change order is signed. This is the discipline that keeps a job within a few percent of the agreed number.
- Lien waiver timing: A conditional lien waiver due at each payment, and a final unconditional waiver at completion. Without it, an unpaid subcontractor can lien your home even after you paid the general contractor in full.
- Written warranty: On roofing, the manufacturer’s warranty plus the contractor’s workmanship warranty, in writing, with the terms attached.
- Deposit limits: Florida statute caps deposits on residential work; know the cap before you write a check.
We quote a flat written price with written scope and written warranty before any work starts, on every trade from Rowan Construction Group Doral home through the full scope of our residential work. After a storm, that habit is the difference between a repair and a fight.
Common Mistakes to Avoid
- Waiting until the storm is named to photograph your home. Your insurer needs pre-loss condition, not post-damage shots. The photos have to predate the wind.
- Storing documentation on a local drive. Flooding takes the drive with it. Cloud storage or nothing.
- Signing a post-storm contract without a written scope. A flat “we’ll fix it for $18,000” with no spec is a dispute waiting to be filed.
- Letting an unlicensed crew start work because they’re available. Unlicensed repairs void future coverage on the same area. The DBPR check takes 60 seconds.
- Skipping the structural engineer after flooding. A contractor who starts rebuild on a shifted slab is building on a moving foundation.
- Treating FEMA as primary coverage. FEMA awards are reduced by insurance settlements; file with your insurer first.
- Paying a storm chaser in cash with no lien waiver. The subcontractor who wasn’t paid can still file a lien against your Doral home.
When to Call a Professional
Call a licensed contractor for any work that involves a roof you can’t safely reach, structural repair, electrical or gas service, or anything on a two-story exterior. File the insurance claim first, then bring in the contractor to scope the repair. For a roof that’s breached, a wall that’s opened, or a foundation that shows the four signs above, the sequence is engineer, then contractor, then repair, and skipping the engineer is where the cost jumps.
If you’re ready to plan the harder exterior items before the next storm rather than after, this is the moment to get them quoted: Driveway & Pavers in Doral for storm-stable hardscape, Fence Installation in Doral for wind-rated fencing, and Home Additions & ADU in Doral for permitted structural work. Rowan Construction Group Doral offers free estimates in Doral. Call (888) 300-3896.
See the difference
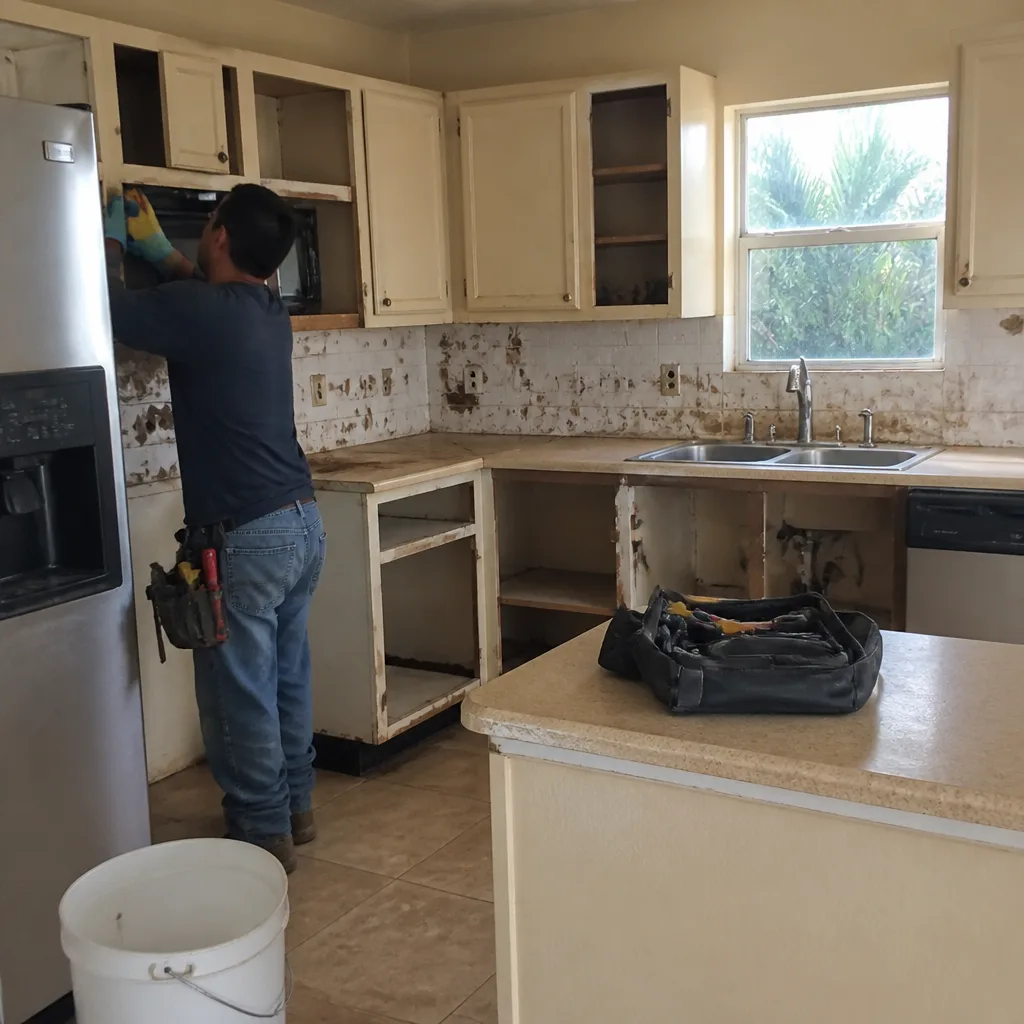 Before
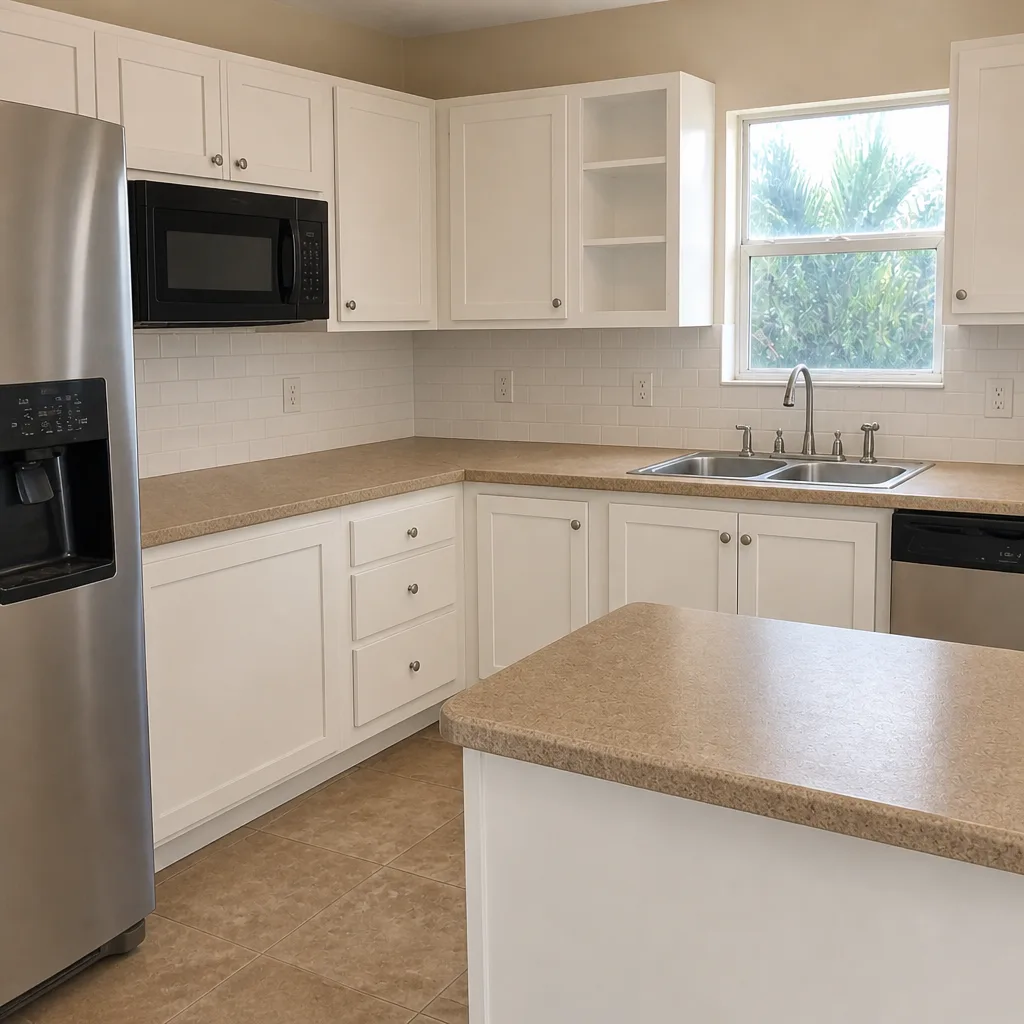 After
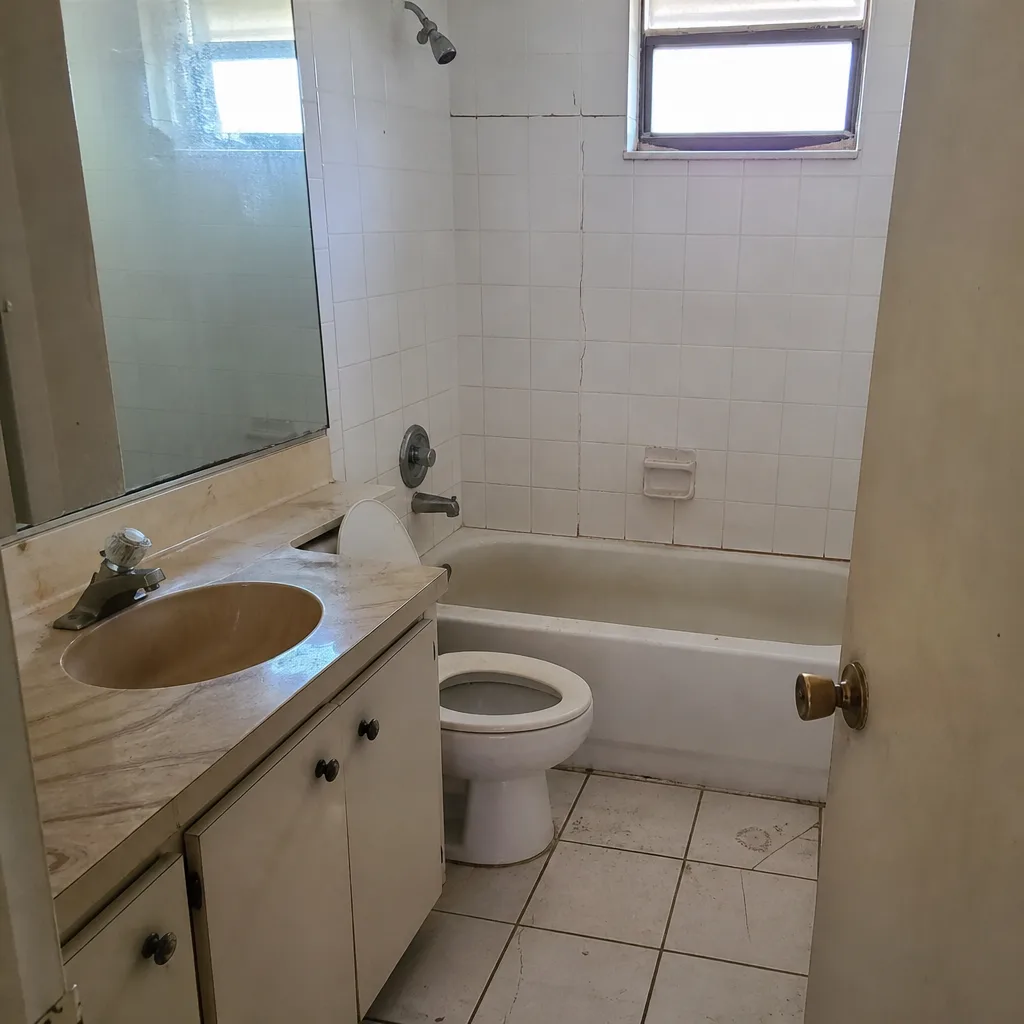 Before
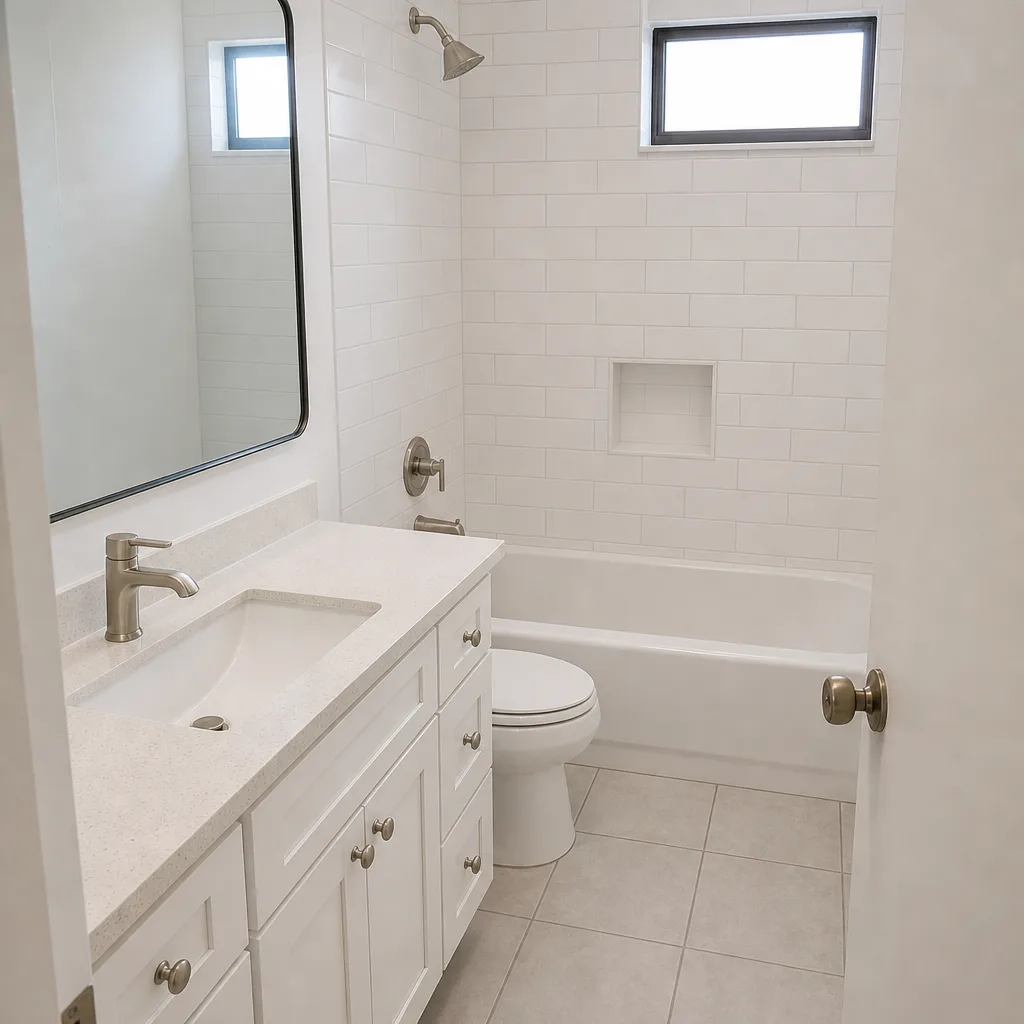 After
 Before
 After
Frequently Asked Questions
Emergency tarping and board-up on a Doral single-family home typically runs $2,500 to $5,000, depending on roof size, pitch, and the number of openings. HO-3 policies generally cover it as mitigation up to policy limits, and you’ll need damage photos before and after to support the reimbursement. Call (888) 300-3896 for a written scope and price before anyone climbs a ladder.
Yes, standard HO-3 policies cover emergency mitigation that prevents further damage, up to policy limits, as long as you document the damage and keep receipts. Full replacement is a separate claim line. The mitigation work itself must be licensed and itemized to be reimbursed.
Search the company or license number at myfloridalicense.com, confirm the license type matches the work, and verify status is “Current, Active.” The check takes under a minute. Unlicensed work can void future insurance coverage on the same part of your home, so the check is worth doing every time.
When you see two or more of the four warning signs: door gaps, diagonal stair-step cracking, windows that suddenly stick, or visible grade separation at the slab edge. A licensed structural engineer evaluates movement and tells you whether re-entry and repair are safe. Skipping this step on a slab-on-grade home can mean rebuilding on a shifted foundation.
FEMA registration needs your Social Security number, insurance policy information, damage photos, proof of occupancy, and a description of the damage. Register at disasterassistance.gov within the 60-day window after the declaration (extensions happen). FEMA covers minimal safe repairs, temporary housing, and essential items, not full reconstruction or code upgrades.
Prepared homes close claims in weeks; unprepared homes take months. The difference is documentation. If you have dated pre-storm photos, a written mitigation scope, and a licensed contractor’s written report, the adjuster can authorize work on the first call. Without that, the claim stalls. Call (888) 300-3896 for a free second opinion on any written estimate before you sign.
The Bottom Line
Doral construction emergencies follow the same pattern every storm: wind damages the roof and windows, water enters, and slab-on-grade homes carry the highest risk of structural movement afterward. The homeowners who recover fastest aren’t luckier. They photographed their home before the storm, stored the files in the cloud, knew their insurer’s claim line, had a written mitigation scope ready, and checked every contractor through the DBPR. Prepare those four things this month and a named storm becomes a project instead of a crisis. Call (888) 300-3896 for a free estimate and a documentation review before the next system forms.
Written by the team at Rowan Construction Group Doral.